Does Homeowners Insurance Cover Foundation Repair in Louisiana?
You found a crack in the slab or a floor that slopes, and the first question is often whether insurance will pay. For homeowners in Shreveport, LA, as elsewhere, the honest answer is "often not, but read your policy." Here is how standard homeowners policies commonly treat foundation damage, where the answer can differ, and how to plan if you end up paying yourself.
Shreveport Foundation Services is a free quote service, not a foundation company. Independent local companies, which may pay to receive requests, reply to homeowners with quotes, and the company you choose does the work. Shreveport Foundation Services is not an insurer or an insurance agent. This is general information, not insurance or legal advice. Your policy and your agent have the final word.
Does homeowners insurance cover foundation repair?
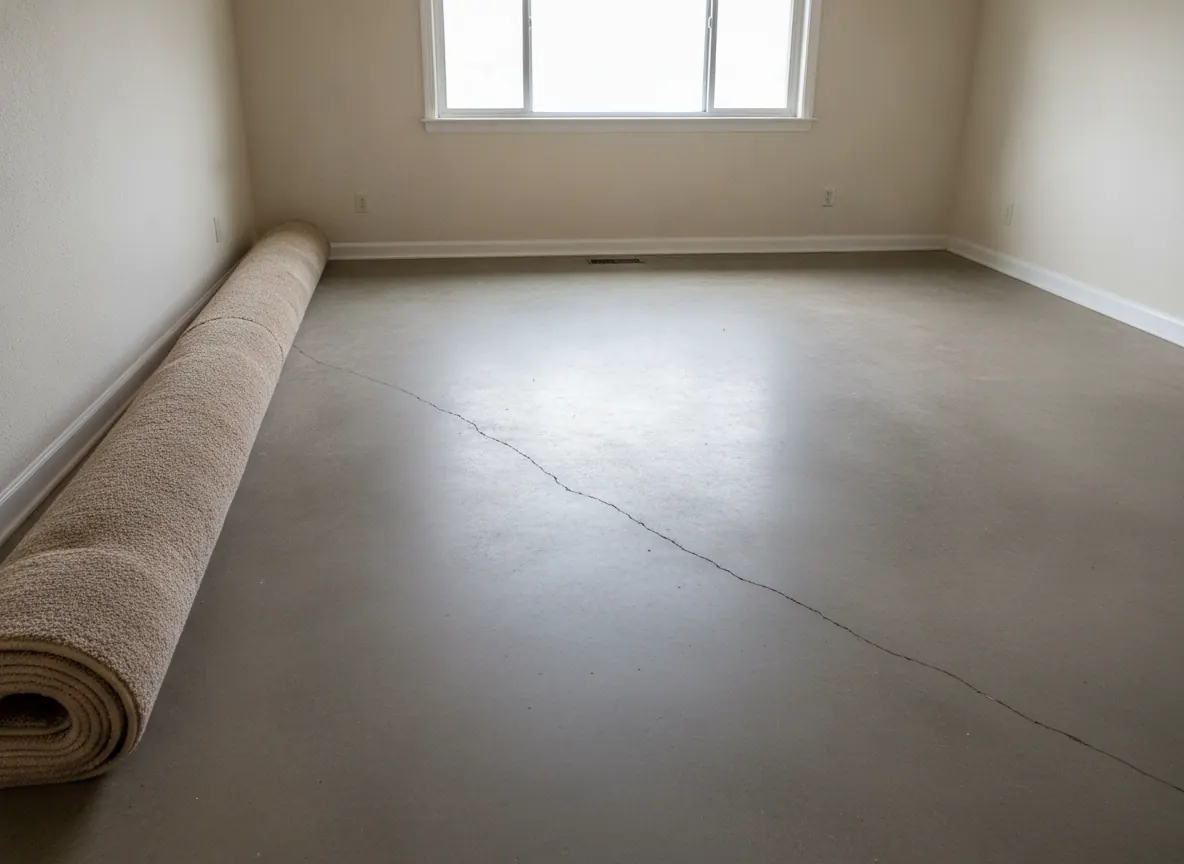
Usually not when the damage comes from the ground slowly moving. Standard homeowners policies commonly exclude settling, earth movement and damage that happens gradually. Foundation movement from clay soil that shrinks and swells, which is common in this region, tends to fall under those exclusions.
Coverage may be different when a sudden event causes the damage, such as a pipe that bursts. Flood damage is a separate matter that needs flood insurance. Policies differ, so read yours and ask your agent before you assume either way.
How policies commonly treat foundation problems
| Situation | How standard policies commonly treat it | What to do |
|---|---|---|
| Cracks from settling or soil shrinking and swelling | Commonly excluded as settling or earth movement | Plan for the repair; get written quotes |
| Slow moisture damage, such as rot in a damp crawl space | Commonly excluded as gradual damage | Fix the moisture source before or with the repair |
| A sudden event, such as a burst pipe | May be treated differently; depends on wording | Document it and call your agent promptly |
| Floodwater from a river, bayou or heavy rain | Needs flood insurance, not homeowners | Check whether you carry a flood policy |
General patterns only. Your policy may read differently.
Why soil movement is usually excluded
Policies commonly treat the slow movement of soil under a house differently from a sudden loss. Around Shreveport, that movement has a well-known driver. Much of Caddo and Bossier parishes is mapped in clay soils with high to very high shrink-swell potential (USDA NRCS soil data): roughly 43% of Caddo and 55% of Bossier by area, including Red River clays like Moreland and Buxin and upland soils like Eastwood and Keithville. Check your own lot on Web Soil Survey. Clay like that swells when wet and shrinks as it dries, which can contribute to foundation movement, and Shreveport's weather swings between a wet April and a hot, dry August (NOAA 1991–2020 normals). Caddo and Bossier parishes each reached D3 "extreme" drought in 2022–2023 (U.S. Drought Monitor). Damage that builds through seasons like those is the kind policies commonly call gradual.
Older homes add to it. Shreveport's median home was built in 1973, and about 65% were built before 1980 (ACS 2020–2024). In many older houses on piers over a crawl space, years of dampness can rot sills and joists, and that kind of slow damage is also commonly excluded. See crawl space repair.
When the answer may be different
A sudden, accidental event is where coverage questions get more interesting. If a supply pipe bursts and soaks the floor, a policy may treat the water damage differently from settling. Whether that extends to the foundation itself depends on how your policy is worded and on what an adjuster finds caused the damage. Under slabs, a company may suggest a plumbing test as part of an inspection, and the result can matter to that conversation.
Ask your agent directly rather than relying on a contractor's opinion of what insurance will pay.
Flooding needs flood insurance
Standard homeowners policies are not where flood damage gets covered; that takes a flood policy. The area has seen real floods. The Red River at Shreveport crested at 37.14 feet on June 10, 2015 (National Weather Service), and NWS reported $8.2 million in property damage in Caddo Parish and $5.6 million in Bossier Parish from that flood. In March 2016, about 18.8 inches of rain fell at Barksdale Air Force Base, and about 3,500 homes in north Bossier City, LA were ordered evacuated, later made voluntary, as Red Chute Bayou neared the top of its levee, according to news reports; the bayou crested at about 25.25 feet without overtopping. If you live near the river or a bayou, ask your agent what a flood policy would and would not cover for your foundation.
Be wary of coverage promises. If anyone tells you insurance will definitely pay for a foundation repair, ask them to put it in writing and then check with your agent. Only your insurer decides a claim. Also follow the Louisiana Attorney General's general advice for repair work: get several written bids and avoid large down payments.
What to read in your policy
- The exclusions section, for words like settling, cracking, shrinking, earth movement and gradual damage.
- The water damage section, for how sudden leaks are treated compared with slow ones.
- Any endorsements or riders you added, since they can change the base policy.
- Whether you carry a separate flood policy, and what it says about foundations.
Then call your agent with specific questions: "If a pipe under my slab bursts, how would my policy treat damage to the slab?" or "Does my policy cover anything for foundation movement?" Ask for the answer in writing.
If you plan to file a claim
Document it
Photograph the damage with a ruler in the frame, write down dates, and mark crack ends.
Call promptly
Ask your agent how and when your policy wants a loss reported.
Get the cause in writing
An independent engineer's report describes what moved and why.
Keep records
Save quotes, reports, permits and receipts in one place.
Because the cause often shapes how damage is treated under a policy, an independent LAPELS-licensed professional engineer's assessment can help you and your agent understand what happened. This Old House puts an inspection at about $300–$1,000. See foundation inspections and structural engineer vs free inspection.
Paying for foundation repair without insurance
If your policy does not cover the repair, you pay for it yourself, so it pays to compare. Typical national ranges from published 2025–2026 cost guides (Fixr, This Old House, Angi), not quotes. Your price depends on an on-site inspection.
| Item | Typical range | Source |
|---|---|---|
| Foundation repair, overall | $2,200–$8,200 (avg ≈ $5,200) | Fixr, Jan 2026 |
| Slab foundation repair | $1,000–$10,000 | Fixr |
| Pier-and-beam foundation repair | $2,000–$15,000 | Fixr |
| Wood rot repair in a crawl space | $750–$5,000 | Fixr |
| Structural engineer inspection | $300–$1,000 (avg ≈ $600) | This Old House, Oct 2026 |
Ask each company for a written scope so you can compare like with like, and ask about the payment schedule. Sometimes a smaller first step, such as fixing drainage and grading, is part of the plan. The Shreveport foundation repair cost guide has more ranges and a calculator, and slab foundation repair covers what slab jobs usually include. When you are ready, request free quotes. Call (318) 633-1685
Frequently asked questions
Does homeowners insurance cover foundation cracks in Louisiana?
Usually not when the cracks come from settling or soil movement. Standard homeowners policies commonly exclude settling, earth movement and gradual damage, and clay-related foundation movement often falls under those exclusions. Damage from a sudden event such as a burst pipe may be treated differently. Read your policy and ask your agent.
Does insurance cover foundation damage from a plumbing leak?
It depends on the policy and on the leak. A sudden event like a burst pipe may be treated differently from a slow leak, which policies commonly treat as gradual damage. Document the damage, report it promptly, and ask your agent how your policy handles damage to the slab itself.
Does homeowners insurance cover flood damage to a foundation?
Flood damage generally needs flood insurance, not a standard homeowners policy. If you live near the Red River, Red Chute Bayou or another flood-prone area around Shreveport and Bossier City, ask your agent whether you carry a flood policy and what it says about foundations.
Should I get an engineer before filing a foundation claim?
It can help. How a policy treats damage often depends on the cause, and an independent LAPELS-licensed engineer's written report describes what moved and why. This Old House lists about $300–$1,000 for an inspection. Ask your agent first whether the insurer will send its own adjuster or engineer.